Friday, October 14, 2011

How to Act on My Most Urgent Warning

 By Brian Hunt, editor in chief, Stansberry & Associates


For much of the past few years, I've been issuing a warning you'll never see in the mainstream press… and most likely never hear it from your broker.

Folks who have heeded my warning have saved a lot of money this year… and should continue to do so.

The warning is that contrary to popular belief, there's little difference in owning stocks or commodities these days.

If you make the popular move of buying a basket of commodities with the belief that you're diversifying your portfolio, you're badly mistaken. You're not diversifying your risk… You're actually "doubling down" on a risky bet. You're betting all will be well with the world and its intertwined economies.

You can see the extraordinary "correlation" between stocks and commodities in the chart below. It plots the performance of the benchmark CRB commodity index (black line) versus the performance of the benchmark S&P 500 index (blue line) over the past year.


The two indexes move in the same up and down fashion, at the same rate. And they've both plummeted since May:


"Interesting," some readers say. "So what should I do about it?"

When structuring your own portfolio, keep correlation in mind… And consider "lightening up" on stocks and commodities.

You could start by just increasing your cash position. I'm not talking about sitting in U.S. dollars for a decade. But in the short term, cash is your "dry powder." It's money you have on hand to buy bargains when they appear. I often call cash "big returns in waiting."

The next thing you can consider is upping your allocation to gold and silver. Granted, gold and silver aren't the screaming deals they were in 2003, but they still have enormous potential to rise, should the U.S. or European sovereign debt situations blow up.

Finally, consider taking a small portion of your portfolio and putting it into a few "short" positions. Short selling is a strategy that allows you to profit when stocks fall. (I read my colleague Porter Stansberry's advisory for the best short-selling ideas. You can learn why here.)

If you've got most of your money in stocks right now with a commodity "hedge," all you've really got is one giant bet on the same thing. For a safer approach, move money to some or all of the alternatives above.

I can't say exactly what your allocation should be. Everyone has different financial needs and goals. And market conditions change constantly.

But in today's age of massive government spending, borrowing, bailouts, and potential blowups, risk-limiting ideas like these have never been more important.

Regards,
Brian Hunt

Tuesday, October 4, 2011

The Stock Market's All Important Chart!

Brian Hunt's
Market Notes

CHART OF THE WEEK: THE STOCK MARKET'S ALL-IMPORTANT BOX

After plummeting 17% in just two weeks, the stock market has formed an extremely important "box." This is the idea behind our chart of the week.

The benchmark S&P 500 stock index spent much of the summer bobbing around the 1,300 level. It reached 1,353 in July. Then the summer crash arrived… and took the index as low as 1,119 (on a closing basis). It has spent the past month flopping up and down in a range between 1,119 and 1,218. Some traders refer to a trading range like this as a "box."

We see the bottom of this box – the 1,119 level – as a "line in the sand" for stocks. If this line is crossed to the downside, it's a major sign the European debt crisis is infecting the rest of the world. It's a major sign the U.S. economy is getting worse.

It's going to be an interesting October…


BThe S&P 500 and its all-important box

Saturday, October 1, 2011

The Greatest Financial Gift You Can Give to Your Children

By Tom Dyson, publisher, The Palm Beach Letter
Saturday, October 1, 2011

I wrote this essay for your children and grandchildren.

You've probably heard about America's huge debt load. The U.S. government's financial obligations now exceed $663,000 per American family. This burden will fall on the youngest Americans.

It's unethical. It's unfortunate. But it's the reality.

With this giant financial obligation bearing down on them, it's critical that now – right now – your children and grandchildren learn about money and finance. They need to know the basic principles… like how to be independent, why debt is dangerous, and how to grow money.

They don't teach finance in schools. If you don't teach them this knowledge, no one will. They call this financial illiteracy.

If our children are financially illiterate, they have as much chance of survival as a swordsman in a gunfight. There will be no mercy for the financially illiterate in the future. It's likely these people will live as indentured servants to the government and its creditors.

But if our kids have a grasp of finance and its basics – and they obey its laws – they will grow up rich. They will be in a position to help other Americans, too.

Below, you'll find the three vital financial concepts all children need to understand. Please pass them on to your children and grandchildren as soon as you can. I have two young children… And these three concepts are my starting point for their financial education.

First of all, our kids must know that they are not entitled to money or wealth… or anything for that matter, even Christmas presents. They must earn money. I want my children to learn that they shouldn't expect anything to be handed to them. I don't want them to rely on the government for their livelihood, like many people do right now.

So many people treat money and prosperity as an entitlement. The government even calls its welfare programs "entitlements." This word – and what it represents – gets stamped into young people's brains. Kids act as if they are somehow entitled to toys, video games, and cars. But why should they be? Just because they have parents, it doesn't mean they should get everything they want… or anything at all, for that matter.

I plan to regularly remind my children of this when they are old enough to understand it. And I'm not going to pay my kids an allowance. An allowance would reinforce the sense of entitlement. They can make money by earning it: doing the dishes, making their beds, mowing the lawn… there are a million things. My wife and I will pay them for doing those things. But I'm not going to just give them money.

The second concept our children need to understand is debt. Debt is expensive. If you abuse it, it will destroy you. Like the entitlement mentality, debt is an enslaver. It robs you of your independence. I avoid debt in my personal life… and when I'm choosing investments.

The best way to illustrate the cost of debt is to calculate the total amount of interest the debt generates in dollars over the lifetime of the loan, instead of looking at the interest rate (like most people do). Once you look at it like that, you can see how expensive borrowing money really is.

For example, say you borrow $100,000 with a 30-year mortgage at 7%. Over 30 years, you'll end up paying $140,000 in interest to the bank. In the end, you're out $240,000 for a house that cost less than half that. Not a good deal.

The third thing our kids need to learn is the power of compound interest and the best way to harness it.

Compound interest is the most powerful force in finance. It is the force behind almost every fortune. The brilliant Richard Russell calls compound interest "The Royal Road to Riches." And it's mathematically guaranteed.

Let's say, for example, you have $100 earning 10% annual interest. At the end of a year, you'll have $110. During the second year, you'll earn interest on $110 instead of $100. In the third year, you'll earn interest on $121… and so on. This is the power of compound interest. The numbers get enormous over time, simply because you're earning interest on your interest.

Because time is the most important element in compounding, it's an incredibly powerful idea for children to understand. They have the ultimate edge in the market: the time to compound over decades.

The stock market is the best place to earn compound interest. You buy companies that have 50 years or more of rising dividend payments ahead of them. Then you let the mathematics work.

As soon as my kids are old enough to understand some arithmetic, I am going to sit down with the classic compounding tables and show them which stocks they have to buy. I'll use Coca-Cola, Johnson & Johnson, and Phillip Morris as examples.

After that, assuming they have the discipline to follow through, they will get rich. There's no doubt about it.

In sum, you have the responsibility to educate your kin about finance. If you don't, no one else will, and they will suffer for it.

Encourage them to work hard and avoid the entitlement mentality. Teach them the power of compound interest and explain the dangers of debt.

If you do this, you will equip your kids and grandkids to survive financially in the difficult circumstances ahead. You'll provide them with something that nobody can place a price on: the power of independence.

Good investing,

Tom

Tuesday, August 23, 2011

The Next Seven Days Will Determine the Market's Fate

From: The Growth Stock Wire


By Jeff Clark
Tuesday, August 23, 2011
It's too early to give up on the bull market.


Yes, all the major averages are down sharply from their April highs, and much of the damage occurred in just the past month. But you can't call it a bear market yet – at least not until the end of the month.


You see, the difference between a bull market and a bear market is just a thin, blue line.


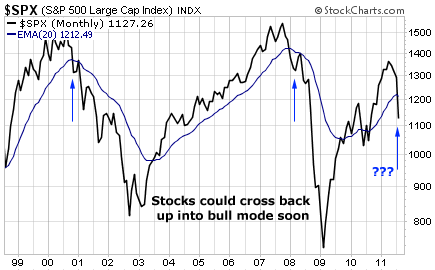
Take a look at the following monthly chart of the S&P 500, plotted against its 20-month exponential moving average (EMA)…


You've seen this chart before. I use it to define bull and bear markets. It's simple to read. If the S&P 500 is trading above its 20-month EMA (the thin, blue line), we're in a bull market. But if the index trades below the line, the bear is in charge.


According to this chart, we're in bear market.


But… not so fast. The market is never that easy to read. Keep in mind… this is a monthly chart. So all that matters is how the S&P closes at the end of the month. Right now, the chart reads bearish. But if the S&P can somehow miraculously rally and close above 1,213 by the end of August, it will erase the breach of the line and the bull will regain control.


It would be just like the stock market to throw us that sort of curveball…


I know the odds are against it. But this week, I'll put my money on the bull. It's too easy to call this a bear market – and too many people are doing just that. So it's time for a strong, counter-trend rally to muddy the waters a bit.


Take another look at the previous chart and notice the action back in August 2000, when we entered a bear market. You can see the breach of the line and the snapback rally that pushed the S&P up to test the breakdown level. The same thing happened in early 2008, just as that bear market was kicking off.


This is important, because even if the market doesn't rally back to the 20-month EMA right now, it will rally at some point. It's normal for prices to come back and test breakdown levels. So we'll likely see the S&P 500 come back over 1,200 at some point.


I'm betting it happens sooner rather than later.


If it happens by the end of the month, the bull will continue to run. You'll want to use any weakness in September as a chance to buy stocks. But if stocks can't rally between now and the end of the month, the bear is back in charge.


Either way, the next seven trading days will determine the market's fate. Keep a close watch on the markets.


Best regard and good trading,


Jeff Clark

Monday, August 22, 2011

The euro crisis is officially worse than 2008

From Pragmatic Capitalism:

One of the many enjoyable acronyms that became household names in 2008 was CDS – credit default swap. As most investors know by now, these instruments were created to protect bondholders from default. Of course, what we found out in 2008 was that they really just shifted the risk from one investor to the other. Sort of like tossing a hand grenade in a circle hoping you aren't the one holding it when it goes boom. And as Wall Street imploded on itself in 2008 this game of toss the grenade became increasingly expensive to play as evidenced by the surging cost to avoid the grenade (surging cost of CDS).
What's frightening about the developments in Europe in recent weeks is that the CDS market is once again sending the same signals. Someone is going to get left holding the grenade again. And this time, the market is actually telling us that it's even worse than it was in 2008. The only difference is that the problems appear to be...
Read full article...
More on the euro crisis:
It's time to be worried about the dollar and the euro
Porter Stansberry: Why stocks are plummeting now
Two of Europe's largest banks are on the "brink of disaster"
View the original article here

Thursday, July 28, 2011

This could be the only way to stop a U.S. credit downgrade

From Washington's Blog:

According to Reuters, a majority of economists now think U.S. credit will be downgraded.

The debt ceiling plans being proposed likely will not avoid a debt downgrade.

Indeed, as Zero Hedge notes, the cuts being proposed in the debt ceiling proposals would be offset by the costs of the downgrade...

The U.S. downgrade alone, now virtually taken for granted by everyone, will offset any beneficial impact from any deficit reduction that will have to happen for the debt ceiling to be increased.

Indeed, many are starting to say a downgrade is inevitable.

In truth and in fact, we could still avoid a downgrade ... but only if we immediately...

Read full article...

More on the "End of America":

Jim Rogers: The U.S. has already lost its triple-A status

Ron Paul BLASTS Obama's fear-mongering on the debt ceiling

The Ron Paul op-ed everyone will be talking about this weekend


View the original article here

Wednesday, July 27, 2011

This chart shows gold will continue its meteoric rise after the debt ceiling is raised

From Resource Investor:

Clearly, a reckless federal government is good for gold – or more accurately, our collective can-kickers in Washington, DC are very bad for the dollar. Take a look at the telling graph below.
Contrary to the disinformation campaign of Wall Street and their Federal Reserve sponsored economists, gold is not a bubble. Central banks are now net buyers of gold... and not because of tradition, as Mr. Bernanke would have you believe.
They are buying gold because...
Read full article...
More on gold:
Top gold miner: QE3 could send gold to $5000, silver to $1000
Gold surges to new all-time high... Silver nears highest price in months
This "shadow gold price" shows just how high precious metals could go
View the original article here